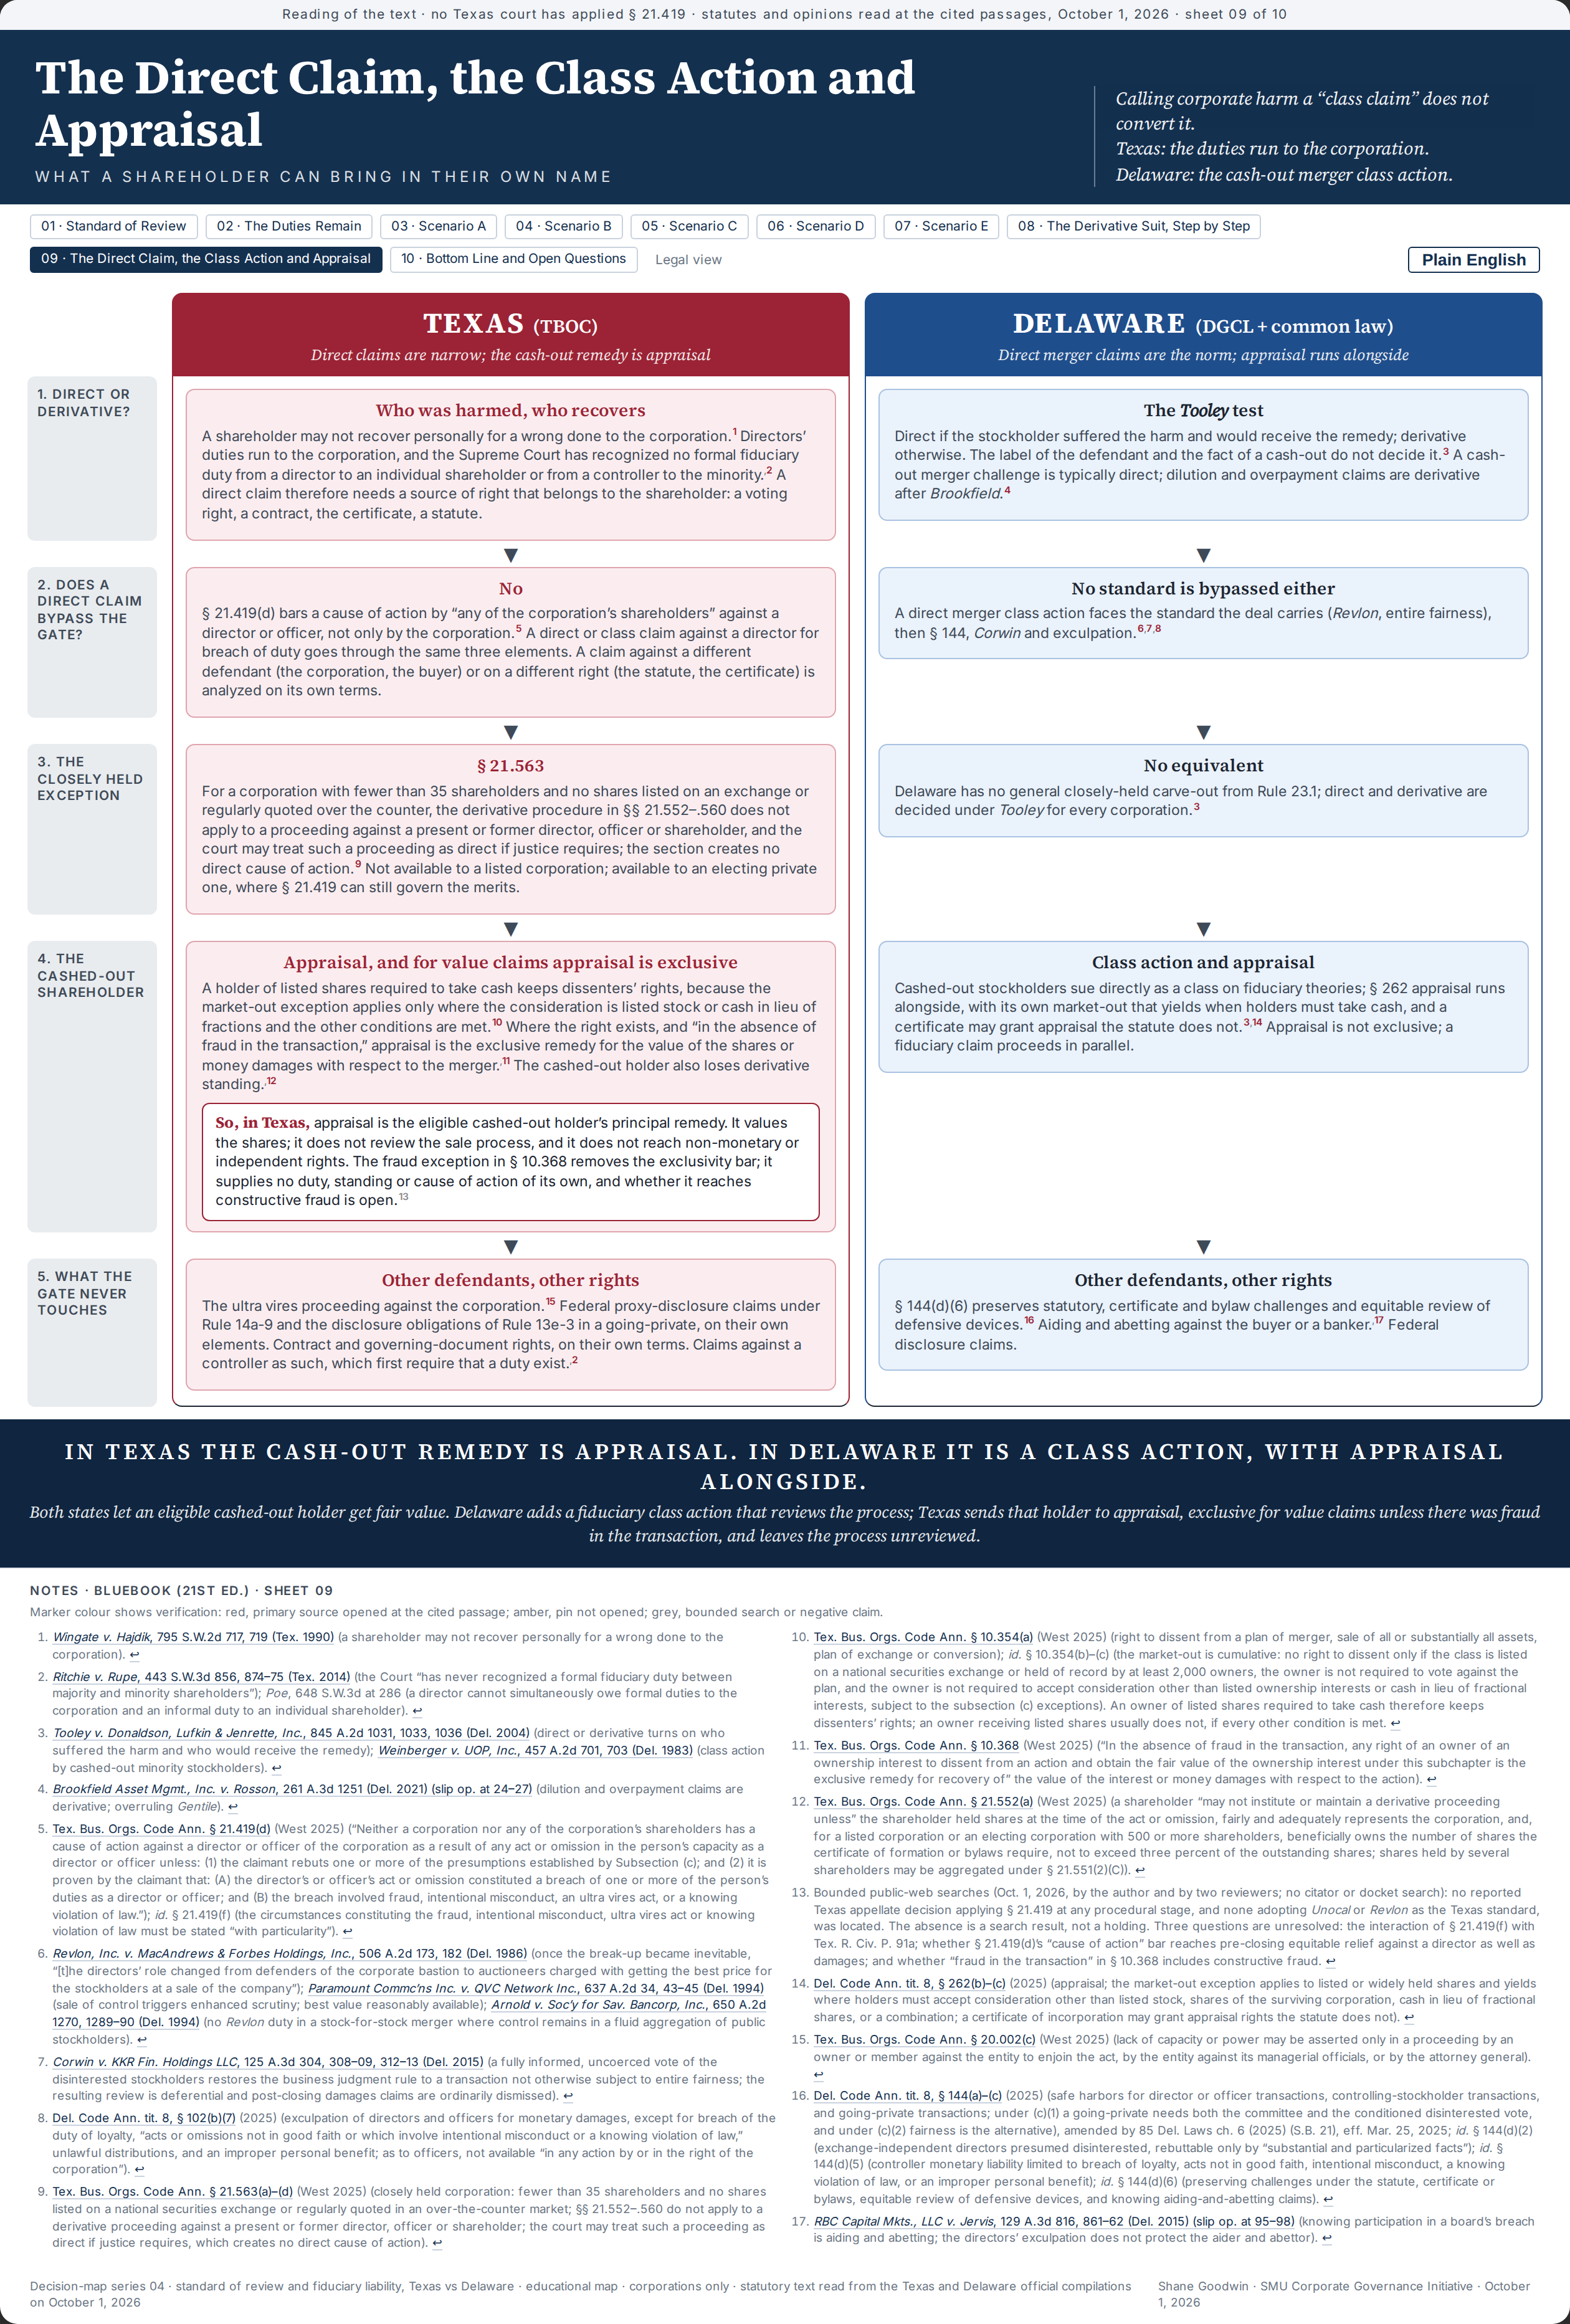
How to read it. Follow either column top to bottom. The grey rail names the question each row answers; the Texas and Delaware columns give each state’s answer with the section or opinion that supplies it. Markers lead to the Bluebook notes under the sheet. The Plain English button at the top of the sheet swaps every cell for an everyday-words version; the legal view and its notes remain the text of record.
The sheets read in order, and each stands alone: 01 and 02 set the frame, 03 to 07 walk one board decision each down both columns, 08 and 09 walk the lawsuit, 10 is the bottom line and the open questions.
Reading of the text · no Texas court has applied § 21.419 · statutes and opinions read at the cited passages, October 1, 2026 · sheet 09 of 10
The Direct Claim, the Class Action and Appraisal
What a shareholder can bring in their own name
Calling corporate harm a “class claim” does not convert it.
Texas: the duties run to the corporation.
Delaware: the cash-out merger class action.
Plain-English view: the same sheet in everyday words, for readers who are not lawyers. It summarizes; the legal view and its notes are the source of record. Click the button again to return.
TEXAS (TBOC)Direct claims are narrow; the cash-out remedy is appraisal
DELAWARE (DGCL + common law)Direct merger claims are the norm; appraisal runs alongside
1. Direct or derivative?
Who was harmed, who recovers
A shareholder may not recover personally for a wrong done to the corporation.1 Directors’ duties run to the corporation, and the Supreme Court has recognized no formal fiduciary duty from a director to an individual shareholder or from a controller to the minority.2 A direct claim therefore needs a source of right that belongs to the shareholder: a voting right, a contract, the certificate, a statute.
A shareholder cannot personally recover for harm done to the company. Texas directors’ duties run to the company, so a personal claim needs its own source: a voting right, a contract, the charter, a statute.
The Tooley test
Direct if the stockholder suffered the harm and would receive the remedy; derivative otherwise. The label of the defendant and the fact of a cash-out do not decide it.3 A cash-out merger challenge is typically direct; dilution and overpayment claims are derivative after Brookfield.4
Delaware asks who was harmed and who would get the money. A cash-out merger challenge is personal; dilution and overpayment claims belong to the company.
2. Does a direct claim bypass the gate?
No
§ 21.419(d) bars a cause of action by “any of the corporation’s shareholders” against a director or officer, not only by the corporation.5 A direct or class claim against a director for breach of duty goes through the same three elements. A claim against a different defendant (the corporation, the buyer) or on a different right (the statute, the certificate) is analyzed on its own terms.
No. The statute bars claims by shareholders as well as by the company. A personal claim against a director goes through the same gate. A claim against someone else, or on a different right, is analyzed on its own.
No standard is bypassed either
A direct merger class action faces the standard the deal carries (Revlon, entire fairness), then § 144, Corwin and exculpation.678
No. A personal merger claim still faces the test the deal carries, then the safe harbors, the informed-vote defense and the charter clause.
3. The closely held exception
§ 21.563
For a corporation with fewer than 35 shareholders and no shares listed on an exchange or regularly quoted over the counter, the derivative procedure in §§ 21.552–.560 does not apply to a proceeding against a present or former director, officer or shareholder, and the court may treat such a proceeding as direct if justice requires; the section creates no direct cause of action.9 Not available to a listed corporation; available to an electing private one, where § 21.419 can still govern the merits.
At small private companies with fewer than 35 shareholders and no listed or regularly quoted shares, the derivative procedure does not apply to claims against current or former directors, officers or shareholders, and a court may treat such a claim as personal if justice requires; this creates no new right to sue.
No equivalent
Delaware has no general closely-held carve-out from Rule 23.1; direct and derivative are decided under Tooley for every corporation.3
Delaware has no general carve-out of that kind.
4. The cashed-out shareholder
Appraisal, and for value claims appraisal is exclusive
A holder of listed shares required to take cash keeps dissenters’ rights, because the market-out exception applies only where the consideration is listed stock or cash in lieu of fractions and the other conditions are met.10 Where the right exists, and “in the absence of fraud in the transaction,” appraisal is the exclusive remedy for the value of the shares or money damages with respect to the merger.11 The cashed-out holder also loses derivative standing.12
So, in Texas, appraisal is the eligible cashed-out holder’s principal remedy. It values the shares; it does not review the sale process, and it does not reach non-monetary or independent rights. The fraud exception in § 10.368 removes the exclusivity bar; it supplies no duty, standing or cause of action of its own, and whether it reaches constructive fraud is open.
13 A shareholder forced to take cash keeps the right to appraisal, and where that right exists it is the only price remedy unless there was fraud in the deal. That shareholder also loses the right to sue on the company’s behalf. Appraisal sets a price; it does not judge how the board ran the sale, so it is the main remedy, not a substitute for Delaware’s class action.
Class action and appraisal
Cashed-out stockholders sue directly as a class on fiduciary theories; § 262 appraisal runs alongside, with its own market-out that yields when holders must take cash, and a certificate may grant appraisal the statute does not.314 Appraisal is not exclusive; a fiduciary claim proceeds in parallel.
Cashed-out shareholders sue directly as a class, and appraisal runs alongside. Appraisal is not the only route.
5. What the gate never touches
Other defendants, other rights
The ultra vires proceeding against the corporation.15 Federal proxy-disclosure claims under Rule 14a-9 and the disclosure obligations of Rule 13e-3 in a going-private, on their own elements. Contract and governing-document rights, on their own terms. Claims against a controller as such, which first require that a duty exist.2
The gate never touches a suit against the company to stop an act beyond its powers, federal disclosure claims, contract claims, or claims against a controlling shareholder, which first require that a duty exist.
Other defendants, other rights
§ 144(d)(6) preserves statutory, certificate and bylaw challenges and equitable review of defensive devices.16 Aiding and abetting against the buyer or a banker.17 Federal disclosure claims.
The safe harbors never touch charter and bylaw challenges, court review of takeover defenses, claims against buyers who knowingly helped, or federal disclosure claims.
IN TEXAS THE CASH-OUT REMEDY IS APPRAISAL. IN DELAWARE IT IS A CLASS ACTION, WITH APPRAISAL ALONGSIDE.Both states let an eligible cashed-out holder get fair value. Delaware adds a fiduciary class action that reviews the process; Texas sends that holder to appraisal, exclusive for value claims unless there was fraud in the transaction, and leaves the process unreviewed.
Notes · Bluebook (21st ed.) · sheet 09
Marker colour shows verification: red, primary source opened at the cited passage; amber, pin not opened; grey, bounded search or negative claim.
- Wingate v. Hajdik, 795 S.W.2d 717, 719 (Tex. 1990) (a shareholder may not recover personally for a wrong done to the corporation). ↩
- Ritchie v. Rupe, 443 S.W.3d 856, 874–75 (Tex. 2014) (the Court “has never recognized a formal fiduciary duty between majority and minority shareholders”); Poe, 648 S.W.3d at 286 (a director cannot simultaneously owe formal duties to the corporation and an informal duty to an individual shareholder). ↩
- Tooley v. Donaldson, Lufkin & Jenrette, Inc., 845 A.2d 1031, 1033, 1036 (Del. 2004) (direct or derivative turns on who suffered the harm and who would receive the remedy); Weinberger v. UOP, Inc., 457 A.2d 701, 703 (Del. 1983) (class action by cashed-out minority stockholders). ↩
- Brookfield Asset Mgmt., Inc. v. Rosson, 261 A.3d 1251 (Del. 2021) (slip op. at 24–27) (dilution and overpayment claims are derivative; overruling Gentile). ↩
- Tex. Bus. Orgs. Code Ann. § 21.419(d) (West 2025) (“Neither a corporation nor any of the corporation’s shareholders has a cause of action against a director or officer of the corporation as a result of any act or omission in the person’s capacity as a director or officer unless: (1) the claimant rebuts one or more of the presumptions established by Subsection (c); and (2) it is proven by the claimant that: (A) the director’s or officer’s act or omission constituted a breach of one or more of the person’s duties as a director or officer; and (B) the breach involved fraud, intentional misconduct, an ultra vires act, or a knowing violation of law.”); id. § 21.419(f) (the circumstances constituting the fraud, intentional misconduct, ultra vires act or knowing violation of law must be stated “with particularity”). ↩
- Revlon, Inc. v. MacAndrews & Forbes Holdings, Inc., 506 A.2d 173, 182 (Del. 1986) (once the break-up became inevitable, “[t]he directors’ role changed from defenders of the corporate bastion to auctioneers charged with getting the best price for the stockholders at a sale of the company”); Paramount Commc’ns Inc. v. QVC Network Inc., 637 A.2d 34, 43–45 (Del. 1994) (sale of control triggers enhanced scrutiny; best value reasonably available); Arnold v. Soc’y for Sav. Bancorp, Inc., 650 A.2d 1270, 1289–90 (Del. 1994) (no Revlon duty in a stock-for-stock merger where control remains in a fluid aggregation of public stockholders). ↩
- Corwin v. KKR Fin. Holdings LLC, 125 A.3d 304, 308–09, 312–13 (Del. 2015) (a fully informed, uncoerced vote of the disinterested stockholders restores the business judgment rule to a transaction not otherwise subject to entire fairness; the resulting review is deferential and post-closing damages claims are ordinarily dismissed). ↩
- Del. Code Ann. tit. 8, § 102(b)(7) (2025) (exculpation of directors and officers for monetary damages, except for breach of the duty of loyalty, “acts or omissions not in good faith or which involve intentional misconduct or a knowing violation of law,” unlawful distributions, and an improper personal benefit; as to officers, not available “in any action by or in the right of the corporation”). ↩
- Tex. Bus. Orgs. Code Ann. § 21.563(a)–(d) (West 2025) (closely held corporation: fewer than 35 shareholders and no shares listed on a national securities exchange or regularly quoted in an over-the-counter market; §§ 21.552–.560 do not apply to a derivative proceeding against a present or former director, officer or shareholder; the court may treat such a proceeding as direct if justice requires, which creates no direct cause of action). ↩
- Tex. Bus. Orgs. Code Ann. § 10.354(a) (West 2025) (right to dissent from a plan of merger, sale of all or substantially all assets, plan of exchange or conversion); id. § 10.354(b)–(c) (the market-out is cumulative: no right to dissent only if the class is listed on a national securities exchange or held of record by at least 2,000 owners, the owner is not required to vote against the plan, and the owner is not required to accept consideration other than listed ownership interests or cash in lieu of fractional interests, subject to the subsection (c) exceptions). An owner of listed shares required to take cash therefore keeps dissenters’ rights; an owner receiving listed shares usually does not, if every other condition is met. ↩
- Tex. Bus. Orgs. Code Ann. § 10.368 (West 2025) (“In the absence of fraud in the transaction, any right of an owner of an ownership interest to dissent from an action and obtain the fair value of the ownership interest under this subchapter is the exclusive remedy for recovery of” the value of the interest or money damages with respect to the action). ↩
- Tex. Bus. Orgs. Code Ann. § 21.552(a) (West 2025) (a shareholder “may not institute or maintain a derivative proceeding unless” the shareholder held shares at the time of the act or omission, fairly and adequately represents the corporation, and, for a listed corporation or an electing corporation with 500 or more shareholders, beneficially owns the number of shares the certificate of formation or bylaws require, not to exceed three percent of the outstanding shares; shares held by several shareholders may be aggregated under § 21.551(2)(C)). ↩
- Bounded public-web searches (Oct. 1, 2026, by the author and by two reviewers; no citator or docket search): no reported Texas appellate decision applying § 21.419 at any procedural stage, and none adopting Unocal or Revlon as the Texas standard, was located. The absence is a search result, not a holding. Three questions are unresolved: the interaction of § 21.419(f) with Tex. R. Civ. P. 91a; whether § 21.419(d)’s “cause of action” bar reaches pre-closing equitable relief against a director as well as damages; and whether “fraud in the transaction” in § 10.368 includes constructive fraud. ↩
- Del. Code Ann. tit. 8, § 262(b)–(c) (2025) (appraisal; the market-out exception applies to listed or widely held shares and yields where holders must accept consideration other than listed stock, shares of the surviving corporation, cash in lieu of fractional shares, or a combination; a certificate of incorporation may grant appraisal rights the statute does not). ↩
- Tex. Bus. Orgs. Code Ann. § 20.002(c) (West 2025) (lack of capacity or power may be asserted only in a proceeding by an owner or member against the entity to enjoin the act, by the entity against its managerial officials, or by the attorney general). ↩
- Del. Code Ann. tit. 8, § 144(a)–(c) (2025) (safe harbors for director or officer transactions, controlling-stockholder transactions, and going-private transactions; under (c)(1) a going-private needs both the committee and the conditioned disinterested vote, and under (c)(2) fairness is the alternative), amended by 85 Del. Laws ch. 6 (2025) (S.B. 21), eff. Mar. 25, 2025; id. § 144(d)(2) (exchange-independent directors presumed disinterested, rebuttable only by “substantial and particularized facts”); id. § 144(d)(5) (controller monetary liability limited to breach of loyalty, acts not in good faith, intentional misconduct, a knowing violation of law, or an improper personal benefit); id. § 144(d)(6) (preserving challenges under the statute, certificate or bylaws, equitable review of defensive devices, and knowing aiding-and-abetting claims). ↩
- RBC Capital Mkts., LLC v. Jervis, 129 A.3d 816, 861–62 (Del. 2015) (slip op. at 95–98) (knowing participation in a board’s breach is aiding and abetting; the directors’ exculpation does not protect the aider and abettor). ↩
Sources behind this sheet (17 notes)
- Wingate v. Hajdik, 795 S.W.2d 717, 719 (Tex. 1990) (a shareholder may not recover personally for a wrong done to the corporation). ↩
- Ritchie v. Rupe, 443 S.W.3d 856, 874–75 (Tex. 2014) (the Court “has never recognized a formal fiduciary duty between majority and minority shareholders”); Poe, 648 S.W.3d at 286 (a director cannot simultaneously owe formal duties to the corporation and an informal duty to an individual shareholder). ↩
- Tooley v. Donaldson, Lufkin & Jenrette, Inc., 845 A.2d 1031, 1033, 1036 (Del. 2004) (direct or derivative turns on who suffered the harm and who would receive the remedy); Weinberger v. UOP, Inc., 457 A.2d 701, 703 (Del. 1983) (class action by cashed-out minority stockholders). ↩
- Brookfield Asset Mgmt., Inc. v. Rosson, 261 A.3d 1251 (Del. 2021) (slip op. at 24–27) (dilution and overpayment claims are derivative; overruling Gentile). ↩
- Tex. Bus. Orgs. Code Ann. § 21.419(d) (West 2025) (“Neither a corporation nor any of the corporation’s shareholders has a cause of action against a director or officer of the corporation as a result of any act or omission in the person’s capacity as a director or officer unless: (1) the claimant rebuts one or more of the presumptions established by Subsection (c); and (2) it is proven by the claimant that: (A) the director’s or officer’s act or omission constituted a breach of one or more of the person’s duties as a director or officer; and (B) the breach involved fraud, intentional misconduct, an ultra vires act, or a knowing violation of law.”); id. § 21.419(f) (the circumstances constituting the fraud, intentional misconduct, ultra vires act or knowing violation of law must be stated “with particularity”). ↩
- Revlon, Inc. v. MacAndrews & Forbes Holdings, Inc., 506 A.2d 173, 182 (Del. 1986) (once the break-up became inevitable, “[t]he directors’ role changed from defenders of the corporate bastion to auctioneers charged with getting the best price for the stockholders at a sale of the company”); Paramount Commc’ns Inc. v. QVC Network Inc., 637 A.2d 34, 43–45 (Del. 1994) (sale of control triggers enhanced scrutiny; best value reasonably available); Arnold v. Soc’y for Sav. Bancorp, Inc., 650 A.2d 1270, 1289–90 (Del. 1994) (no Revlon duty in a stock-for-stock merger where control remains in a fluid aggregation of public stockholders). ↩
- Corwin v. KKR Fin. Holdings LLC, 125 A.3d 304, 308–09, 312–13 (Del. 2015) (a fully informed, uncoerced vote of the disinterested stockholders restores the business judgment rule to a transaction not otherwise subject to entire fairness; the resulting review is deferential and post-closing damages claims are ordinarily dismissed). ↩
- Del. Code Ann. tit. 8, § 102(b)(7) (2025) (exculpation of directors and officers for monetary damages, except for breach of the duty of loyalty, “acts or omissions not in good faith or which involve intentional misconduct or a knowing violation of law,” unlawful distributions, and an improper personal benefit; as to officers, not available “in any action by or in the right of the corporation”). ↩
- Tex. Bus. Orgs. Code Ann. § 21.563(a)–(d) (West 2025) (closely held corporation: fewer than 35 shareholders and no shares listed on a national securities exchange or regularly quoted in an over-the-counter market; §§ 21.552–.560 do not apply to a derivative proceeding against a present or former director, officer or shareholder; the court may treat such a proceeding as direct if justice requires, which creates no direct cause of action). ↩
- Tex. Bus. Orgs. Code Ann. § 10.354(a) (West 2025) (right to dissent from a plan of merger, sale of all or substantially all assets, plan of exchange or conversion); id. § 10.354(b)–(c) (the market-out is cumulative: no right to dissent only if the class is listed on a national securities exchange or held of record by at least 2,000 owners, the owner is not required to vote against the plan, and the owner is not required to accept consideration other than listed ownership interests or cash in lieu of fractional interests, subject to the subsection (c) exceptions). An owner of listed shares required to take cash therefore keeps dissenters’ rights; an owner receiving listed shares usually does not, if every other condition is met. ↩
- Tex. Bus. Orgs. Code Ann. § 10.368 (West 2025) (“In the absence of fraud in the transaction, any right of an owner of an ownership interest to dissent from an action and obtain the fair value of the ownership interest under this subchapter is the exclusive remedy for recovery of” the value of the interest or money damages with respect to the action). ↩
- Tex. Bus. Orgs. Code Ann. § 21.552(a) (West 2025) (a shareholder “may not institute or maintain a derivative proceeding unless” the shareholder held shares at the time of the act or omission, fairly and adequately represents the corporation, and, for a listed corporation or an electing corporation with 500 or more shareholders, beneficially owns the number of shares the certificate of formation or bylaws require, not to exceed three percent of the outstanding shares; shares held by several shareholders may be aggregated under § 21.551(2)(C)). ↩
- Bounded public-web searches (Oct. 1, 2026, by the author and by two reviewers; no citator or docket search): no reported Texas appellate decision applying § 21.419 at any procedural stage, and none adopting Unocal or Revlon as the Texas standard, was located. The absence is a search result, not a holding. Three questions are unresolved: the interaction of § 21.419(f) with Tex. R. Civ. P. 91a; whether § 21.419(d)’s “cause of action” bar reaches pre-closing equitable relief against a director as well as damages; and whether “fraud in the transaction” in § 10.368 includes constructive fraud. ↩
- Del. Code Ann. tit. 8, § 262(b)–(c) (2025) (appraisal; the market-out exception applies to listed or widely held shares and yields where holders must accept consideration other than listed stock, shares of the surviving corporation, cash in lieu of fractional shares, or a combination; a certificate of incorporation may grant appraisal rights the statute does not). ↩
- Tex. Bus. Orgs. Code Ann. § 20.002(c) (West 2025) (lack of capacity or power may be asserted only in a proceeding by an owner or member against the entity to enjoin the act, by the entity against its managerial officials, or by the attorney general). ↩
- Del. Code Ann. tit. 8, § 144(a)–(c) (2025) (safe harbors for director or officer transactions, controlling-stockholder transactions, and going-private transactions; under (c)(1) a going-private needs both the committee and the conditioned disinterested vote, and under (c)(2) fairness is the alternative), amended by 85 Del. Laws ch. 6 (2025) (S.B. 21), eff. Mar. 25, 2025; id. § 144(d)(2) (exchange-independent directors presumed disinterested, rebuttable only by “substantial and particularized facts”); id. § 144(d)(5) (controller monetary liability limited to breach of loyalty, acts not in good faith, intentional misconduct, a knowing violation of law, or an improper personal benefit); id. § 144(d)(6) (preserving challenges under the statute, certificate or bylaws, equitable review of defensive devices, and knowing aiding-and-abetting claims). ↩
- RBC Capital Mkts., LLC v. Jervis, 129 A.3d 816, 861–62 (Del. 2015) (slip op. at 95–98) (knowing participation in a board’s breach is aiding and abetting; the directors’ exculpation does not protect the aider and abettor). ↩
Decision-map series 04 · standard of review and fiduciary liability, Texas vs Delaware · educational map · corporations only · statutory text read from the Texas and Delaware official compilations on October 1, 2026Shane Goodwin · SMU Corporate Governance Initiative · October 1, 2026
Read the statutes and the opinions
- Tex. S.B. 29, 89th Leg., R.S. (2025) (enrolled) — §§ 21.416(g), 21.4161, 21.418, 21.419, 21.552, 2.115, 2.116, eff. May 14, 2025.
- Tex. Bus. Orgs. Code § 21.419 (the liability gate); § 21.401 (what a board may consider); § 21.418 (interested directors and officers); §§ 21.551–21.563 (derivative proceedings); § 7.001 (exculpation); § 20.002 (ultra vires); §§ 10.354 and 10.368 (dissent and appraisal); § 1.057 (construction).
- Del. Code Ann. tit. 8, § 144 (as amended by 85 Del. Laws c. 6, S.B. 21, eff. Mar. 25, 2025); § 102(b)(7) (exculpation); § 262 (appraisal).
- Delaware: Aronson v. Lewis, 473 A.2d 805 (Del. 1984); Unocal Corp. v. Mesa Petroleum Co., 493 A.2d 946 (Del. 1985); Revlon, Inc. v. MacAndrews & Forbes Holdings, Inc., 506 A.2d 173 (Del. 1986); Paramount Communications Inc. v. QVC Network Inc., 637 A.2d 34 (Del. 1994); Weinberger v. UOP, Inc., 457 A.2d 701 (Del. 1983); Cede & Co. v. Technicolor, Inc., 634 A.2d 345 (Del. 1993); Zapata Corp. v. Maldonado, 430 A.2d 779 (Del. 1981); RBC Capital Markets, LLC v. Jervis, 129 A.3d 816 (Del. 2015); Lyondell Chemical Co. v. Ryan, 970 A.2d 235 (Del. 2009); Corwin v. KKR Financial Holdings LLC, 125 A.3d 304 (Del. 2015); Stone v. Ritter, 911 A.2d 362 (Del. 2006); Tooley v. Donaldson, Lufkin & Jenrette, Inc., 845 A.2d 1031 (Del. 2004); Brookfield Asset Management, Inc. v. Rosson, 261 A.3d 1251 (Del. 2021); United Food & Commercial Workers Union v. Zuckerberg, 262 A.3d 1034 (Del. 2021); Dodiya v. Franklin, C.A. No. 2025-0932-LWW (Del. Ch. Aug. 26, 2026).
- Texas: In re Estate of Poe, 648 S.W.3d 277 (Tex. 2022); Ritchie v. Rupe, 443 S.W.3d 856 (Tex. 2014); Sneed v. Webre, 465 S.W.3d 169 (Tex. 2015); Gearhart Industries, Inc. v. Smith International, Inc., 741 F.2d 707 (5th Cir. 1984); Wingate v. Hajdik, 795 S.W.2d 717 (Tex. 1990); International Bankers Life Insurance Co. v. Holloway, 368 S.W.2d 567 (Tex. 1963); Cates v. Sparkman, 73 Tex. 619, 11 S.W. 846 (1889); Gusinsky v. Reynolds, No. 3:25-cv-01816-K (N.D. Tex. Mar. 17, 2026). Each sheet carries its own Bluebook notes beneath the chart, with a link to each opinion; the marker colour says whether the cited passage was opened. Opinions are collected on the vertical’s sources page.
Educational map. Corporations only; LLC and partnership analogues differ. A reading of the statutory text: no Texas court has applied § 21.419 to a sale, a defense or a conflicted deal. Nothing here is legal advice.